The value of earnings per kilometre in the road transport sector
Given the ongoing discussions about logistics efficiency, diesel price volatility and the broader freight performance outlook in South Africa, Dealerfloor publish commentary from Banie Claasen, Managing Executive for Specialised Lending Products at Absa Business Banking on this important topic.
Share with friends
South Africa is blessed with an expansive 750 000km road network, the largest in Africa and the tenth largest in the world. Naturally, road dominates freight movement, with an 80% market share, making it the biggest subsector in transport.
Road transport operators managing fleets of all sizes, from interlink trucks and tautliners to flatbeds, refrigerated units, bulk tankers, car carriers and other specialised vehicles, are the animating force of this economy. They haul everything we and the country need.
But the industry has experienced its share of ups and downs. According to the C-Track Transport and Freight Index (TFI), which measures the sector's performance, there was 2.4% growth in the first quarter of this year, but a slower rate of 0.8% in the second, in line with GDP.
To make it in the tough road freight industry where internal and external factors compress margins, operators need smart fleet management strategies.
Banie Claasen (Managing Executive for Specialised Lending Products at Absa Business Banking).
Earnings Per Kilometre (EPK) is a profitability metric that shows how much revenue a vehicle generates per kilometre travelled. It helps operators assess whether their pricing strategies, fleet utilisation and cost management align with sustainable profitability.
The going rate per kilometre varies depending on the route, the type of commodity and various other factors. So, what are the revenue-side and cost-side pressures that eat into this thin EPK margin for operators?
On the revenue side, intense competition in road freight and logistics keeps rates under pressure. Road freight hauling is an open market marked by intense competition among operators. Those who overprice are quickly replaced by cheaper competitors. There is over-capacity in certain corridors, most notably, the container corridor between Johannesburg and Durban, pushing prices down.
Macroeconomic factors such as the slowdown in economic growth and lower consumer demand also add to revenue pressure and thinning margins. For example, volatility in global trade has negatively affected domestic transport and logistics. Take the reciprocal tariffs by the Trump administration on key SA imports, which have had a knock-on effect on local automotive sectors.
On the cost side, fuel remains the most immediate saboteur of Cost per Kilometre (CPK). It is a dominant driver, accounting for up to 55% of operational costs. The recovery of the rand against the US Dollar has pushed the diesel price slightly down.
An increase in the cost of vehicle parts, maintenance and repair charges, higher wages, rising insurance premiums, tolls and road charges, and the financing costs of fleet acquisition or expansion, all also have a negative net impact on CPK.
It is critical that transport operators choose the right partner who can offer financial solutions tailor-made for success in this intensely competitive and volatile industry. The right partner can help operators craft fleet optimisation strategies and offer transactional tools that help ease operational cost pressures, actively manage the total cost of ownership and ensure a future-fit replacement strategy.
For transporters looking to expand or modernise their fleets, long-term lending packages at reasonable interest rates assist in the sustainable management of costs. Automated fleet management systems and fuel efficiency measures encompassing telematics, route optimisation and driver training to reduce fuel burn can also result in significant operational cost savings. This has also led to higher demand for full maintenance lease solutions whereby the fleet operator prefers a risk prevention strategy and focus on fleet efficiencies and not ownership.
Of course, an operator could choose to go it alone. However, those who seek to maximise efficiencies will understand the added value of choosing the right partner. A partner who understands the needs of the sector can offer strategic advice when it comes to contract renegotiation; for example, linking tariffs to fuel indices or the Consumer Price Index (CPI) to hedge against cost increases.
Buyers with a budget but no shortlist are getting more help, and dealers have a few changes of their own to look forward to. In this article, sponsored by AutoTrader, we look at how AutoTrader is changing how buyers find cars and how dealers get them advertised.
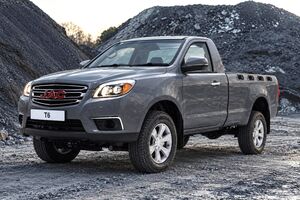
JAC Motors South Africa has launched the T6 2.0L CTi 4x4 single cab bakkie, ten months after the T6 4x2 arrived in January. The T6 4x4 was first sold locally as a double cab in 2017, and it now enters the single cab segment. With this addition, the T-Series offers 4x4 derivatives across the T6, T8 and T9 ranges.
Cheap labour and state subsidies are the usual explanations for Chinese car prices. Research from think tanks and universities suggest the answer is far more complicated.
Cheap labour and state subsidies are the usual explanations for Chinese car prices. Research from think tanks and universities suggest the answer is far more complicated.
The first Volkswagen Tengo destined for an African customer rolled off the production line at Plant Kariega on 9 November 2026, making history in more ways than one.